01
Canadians moving to or working in the U.S.
Departure tax, residency tie-breakers, TN and H-1B employees, and the first dual-status year.
Cross-border tax handled by licensed CPAs on both sides of the border — a Toronto CPA for Canada, a New York CPA for the U.S., and one coordinated plan so nothing falls between them.
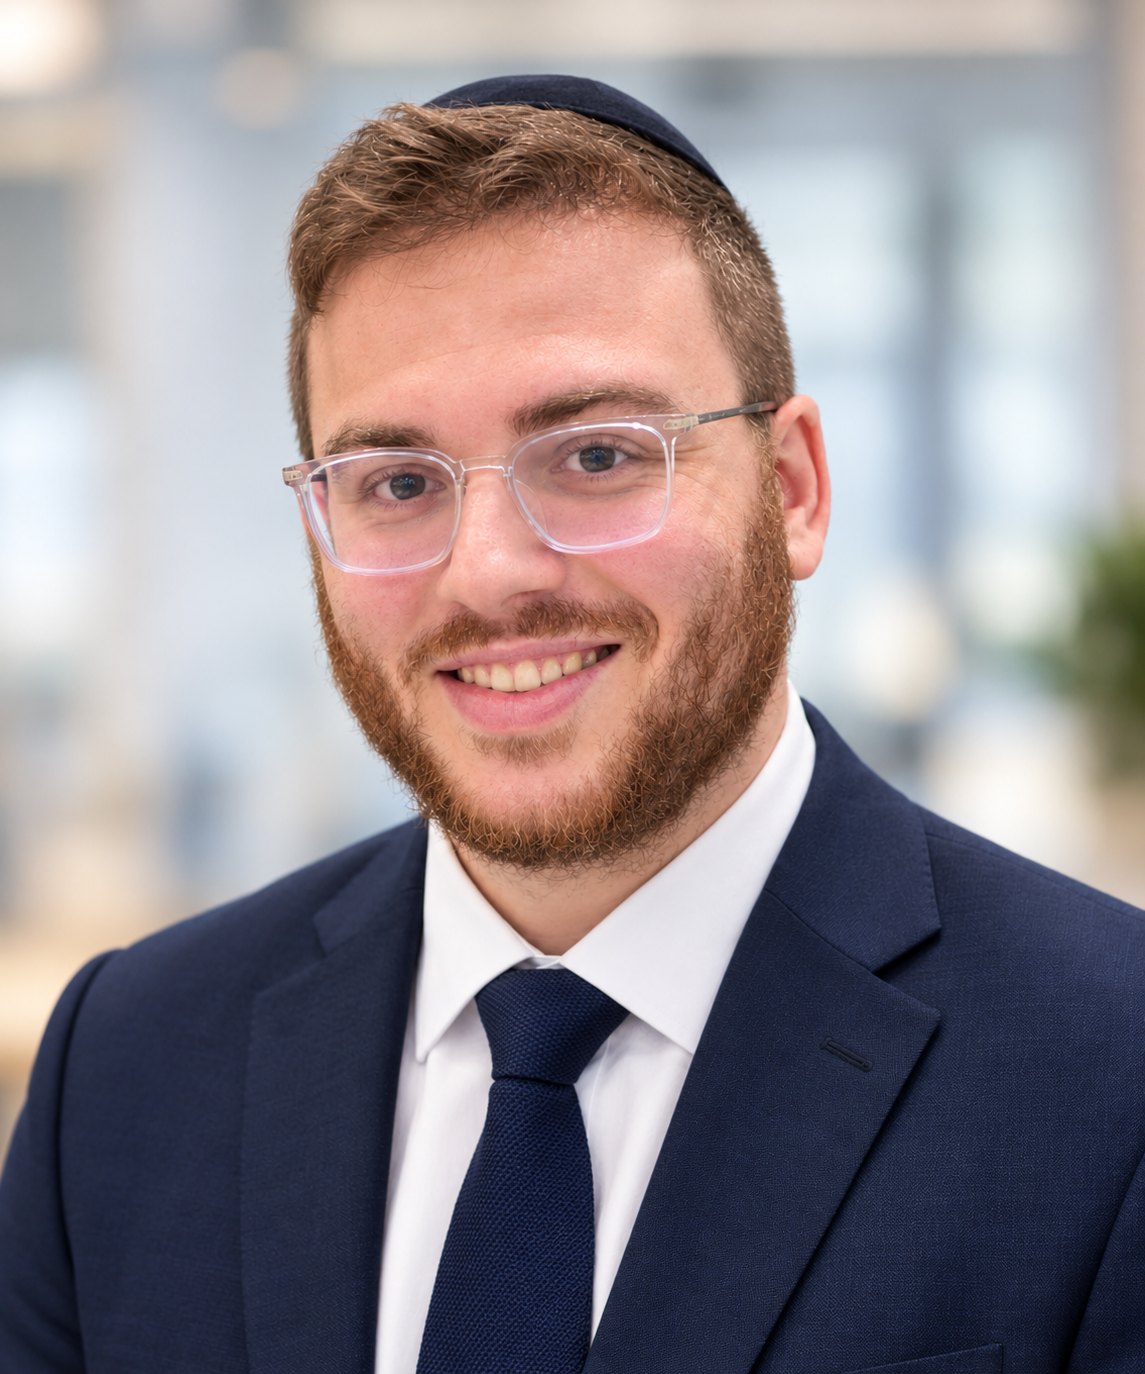
Mendel leads the Canadian side of every cross-border engagement. A Toronto-based Chartered Professional Accountant with extensive tax and audit experience, he brings an auditor's discipline to Canadian compliance and a tax planner's instinct to the structures that sit on both sides of the border.
He works directly with Yisroel Meroz, CPA in New York, so your Canadian and U.S. positions are built together — treaty elections, foreign tax credits, and reporting deadlines reconciled before anything is filed.
The most expensive cross-border mistakes are the quiet ones — a form nobody mentioned, an election nobody made. We look for them first.
Departure tax, residency tie-breakers, TN and H-1B employees, and the first dual-status year.
U.S. citizens and green-card holders who still file a 1040 every year — plus FBAR, 8938, and the Canadian side.
Canadian companies selling into the U.S., U.S. companies hiring in Canada, and the entity choices that follow.
Rental property, a cottage, or a condo on the other side of the line — and the withholding rules on sale.
Every item below is prepared by the CPA licensed in that country and reviewed against the other country's return before filing.
U.S. Form 1040 / 1040-NR alongside the Canadian T1, with foreign tax credits worked out so you're not taxed twice on the same dollar.
Canada–U.S. tax treaty positions, tie-breaker residency analysis, and the elections that decide which country taxes what.
FBAR (FinCEN 114), Form 8938, Forms 5471 / 8865 / 3520 on the U.S. side; T1135 and T1134 on the Canadian side. The penalty forms, done right.
C-corp, LLC, S-corp, or Canadian corporation — chosen with both tax systems in view. (Canadians: we'll explain why an LLC is often the wrong answer.)
Canadian departure tax and deemed dispositions, U.S. arrival planning, RRSP / TFSA / 401(k) treatment, and the dual-status year.
FIRPTA on U.S. property, Section 116 certificates on Canadian property, and rental-income elections (1040-NR, Section 216) so cash isn't stuck in withholding.
Employees on one side, employer on the other: payroll registration, withholding, and the permanent-establishment questions that come with it.
Missed years on either side. IRS Streamlined Filing and CRA Voluntary Disclosure, handled quietly and completely.
One intake call with both offices. We establish residency, list every filing obligation in each country, and flag anything already overdue.
A single scope, fixed price, and deadline calendar covering CRA and IRS. Treaty positions and credits are agreed before the first return is prepared.
Returns are prepared in the right order so each one feeds the other, cross-reviewed by both CPAs, and filed. Then we stay on the file year-round.
Yes — every year, on worldwide income, regardless of where you live. Foreign tax credits and the treaty usually mean little or no U.S. tax is owed, but the return and the foreign-account reports are still required.
Rarely, when the two returns are coordinated. Most double tax comes from returns prepared in isolation — credits claimed in the wrong country, or income sourced inconsistently between the two.
An RRSP, generally yes, with treaty-protected deferral. A TFSA has no U.S. equivalent and is usually taxable in the U.S. — often worth closing before you move. We'll walk through each account.
Usually not. The CRA treats a U.S. LLC as a corporation, which can strip away the foreign tax credit and create double tax. A C-corp or a different structure is often the better fit — we'll model both.
With a quiet, confidential conversation. Both the IRS and CRA have voluntary programs that can reduce or remove penalties when you come forward before they contact you.
No. That's the point of this page. One engagement letter, one point of contact, and licensed CPAs on each side of the border who already talk to each other.
Free 30-minute consultation with the firm. We'll listen, map your obligations in both countries, and tell you honestly what's needed.